India’s F&O market has an extraordinary concentration near expiry.
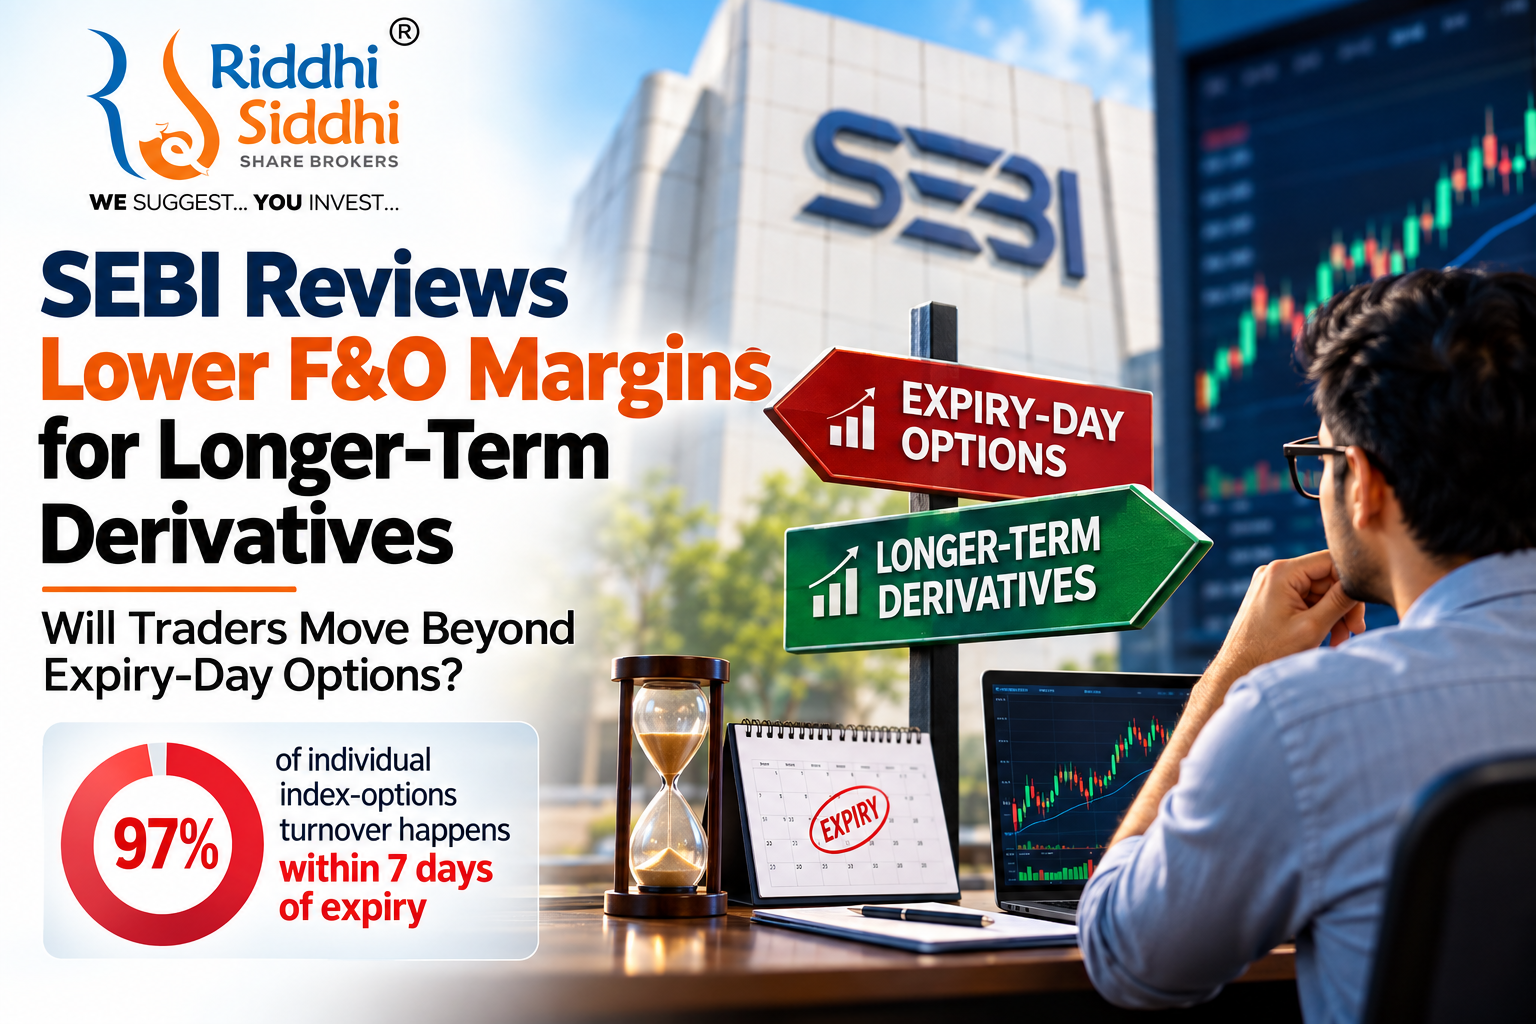
Approximately 59% of individual index-options turnover occurs on the day of expiry, while around 97% occurs within seven days of expiry.
Now, the Securities and Exchange Board of India (SEBI) is examining whether margin requirements for longer-term derivative contracts can be rationalised or potentially reduced.
That raises a much bigger question:
Could India’s F&O market gradually move beyond its overwhelming concentration around expiry-day and near-expiry options?
Before answering that, one point is critical.
What Has Changed in F&O Margins Today?
Nothing yet.
SEBI Chairman Tuhin Kanta Pandey said on September 23, 2026 that the regulator is open to reviewing and potentially lowering margin requirements for longer-tenure derivative products to encourage healthier, longer-term participation.
However:
- No new margin percentage has been announced.
- No qualifying contract tenure has been specified.
- No implementation date has been announced.
- No new margin framework has taken effect.
Therefore, existing margin requirements continue to apply.
This is a regulatory review under consideration — not an announced F&O margin cut.
That distinction matters for every trader reading the headlines.
Why Is SEBI Looking at Longer-Term Derivatives?
Derivatives are not merely speculative instruments.
Futures and options can be used by investors, institutions and businesses for hedging, portfolio risk management and managing exposure to market movements.
SEBI itself has previously highlighted the development of longer-term futures and options as part of deepening India’s capital markets.
The challenge is the extraordinary concentration of individual trading activity in very short-duration index options.
As explained in Riddhi Siddhi Share Brokers’ detailed analysis, nearly 88% of individual F&O traders lost money in FY26.
SEBI’s FY25–FY26 studies found:
- 87.7% of individual equity-derivatives traders incurred net losses
- Aggregate individual net losses were approximately ₹91,685 crore
- Individual transaction costs were approximately ₹25,000 crore
- Approximately 59% of individual index-options turnover occurred on expiry day
- Approximately 97% occurred within seven days of expiry
These numbers tell us something beyond how much money individual traders lost.
They show just how heavily index-options activity among individuals is concentrated close to expiry.
97% Within Seven Days: Why Does It Matter?
Options behave differently as they move closer to expiry.
Time value generally declines as an option approaches expiration. This is associated with theta, or time decay.
But theta is only one consideration.
Near-expiry options can also react very sharply to movements in the underlying index, changes in implied volatility and shifting market expectations.
This combination can produce rapid percentage changes in option premiums.
That is one reason short-duration options attract traders looking for quick market opportunities.
It is also one reason these contracts can be extremely unforgiving when the market moves differently from expectations.
The concentration of approximately 97% of individual index-options turnover within seven days of expiry therefore provides important context for the discussion around developing deeper longer-duration derivatives markets.
What Could Lower Margins for Longer-Term F&O Do?
Margin determines how much capital a market participant needs to maintain certain derivative positions.
If SEBI eventually rationalises margins for eligible longer-tenure derivative contracts, it could alter the capital economics of holding those positions.
Potential implications could include:
1. Encouraging Longer-Term Hedging
Investors and institutions looking to protect portfolios over several weeks or months may find longer-duration contracts more practical if capital requirements become more efficient.
2. Supporting Portfolio Risk Management
Longer-tenure derivatives can potentially help participants manage portfolio exposure without repeatedly rolling very short-duration contracts.
3. Improving Longer-Dated F&O Liquidity
Greater participation could potentially improve liquidity and market depth in longer-duration contracts over time.
But none of these outcomes is automatic.
Liquidity, bid-ask spreads, volatility, market-maker participation, transaction costs and the final regulatory framework would all matter.
Does Lower Margin Mean Lower Risk?
No.
This is perhaps the most important distinction for individual traders.
If margin requirements for certain longer-term contracts are eventually reduced, it would mean less capital may be required to maintain an eligible position.
It does not mean the derivative itself has become safer.
In fact, obtaining the same market exposure with less capital can increase effective leverage.
And leverage can magnify both profits and losses.
Remember:
Margin requirement = capital required to maintain a position.
Market risk = the potential financial loss arising from that position.
Reducing the first does not automatically reduce the second.
Long-Dated Options vs Near-Expiry Options
| Factor | Near-Expiry Options | Longer-Dated Options |
|---|---|---|
| Time to expiry | Short | Longer |
| Time decay | Can become particularly significant near expiry | Spread across a longer remaining period, though theta still applies |
| Price sensitivity | Can move extremely rapidly near expiry | Different sensitivity because more time remains |
| Liquidity | Often high in popular near-expiry index contracts | Can vary significantly by contract and maturity |
| Hedging horizon | Primarily short-term | Potentially better aligned with longer-duration exposure |
| Option premium | Can be lower because little time remains | Generally includes greater time value |
| Risk | Rapid premium changes can occur | Market, volatility and leverage risks remain significant |
Neither is inherently “better”.
They have different characteristics, purposes and risks.
Could Traders Actually Move Away From Expiry-Day Options?
Possibly — but margins alone are unlikely to determine behaviour.
Near-expiry options are popular for several reasons, including liquidity, relatively low absolute option premiums, short holding periods and the potential for large percentage movements.
Making longer-duration contracts more capital-efficient could influence behaviour.
However, whether there is a meaningful shift will depend on:
- the actual margin changes, if any,
- which contracts qualify,
- liquidity,
- spreads,
- transaction costs,
- market-maker participation, and
- how traders and institutional participants respond.
It would therefore be premature to conclude that expiry-day trading is about to disappear.
This Is Part of a Bigger Change in India’s Derivatives Market
SEBI’s latest comments should not be viewed in isolation.
The regulator has been reviewing multiple aspects of India’s derivatives ecosystem while simultaneously emphasising the need for deeper capital markets and effective risk management.
Riddhi Siddhi Share Brokers has previously explained some of these structural developments in our analysis of new stock-market and F&O rules.
There is also an important business dimension.
Derivatives volumes are economically significant for India’s stock exchanges. VaultStreet Advisors’ NSE vs BSE FY26 comparison explains the scale of NSE’s derivatives market share and why changes in derivatives regulation can also matter when evaluating the economics and regulatory risks of exchange businesses.
The broader regulatory challenge is therefore to balance several objectives:
- maintain deep and efficient derivatives markets,
- enable legitimate hedging,
- improve market stability,
- address excessive speculative activity,
- deepen longer-duration markets, and
- improve investor understanding of derivatives risk.
What Should F&O Traders Do Right Now?
The answer is straightforward:
Do not restructure your trading strategy simply because SEBI is examining this possibility.
There is no announced new margin percentage or implementation date.
If SEBI or the exchanges subsequently issue circulars changing margin requirements, traders should examine the actual framework before assessing its impact.
Until then, existing requirements remain relevant.
More importantly, F&O traders should continue focusing on factors that matter regardless of the margin regime:
- position sizing,
- maximum acceptable loss,
- leverage,
- liquidity,
- time to expiry,
- volatility,
- stop-loss discipline, and
- overall capital allocation.
Readers who want to understand the fundamentals can also explore Riddhi Siddhi Share Brokers’ guide to derivatives trading and Futures & Options.
What Could This Mean for India’s F&O Market?
SEBI’s latest comments are interesting not because F&O margins have already changed.
They have not.
The bigger story is what the discussion tells us about the possible future structure of India’s derivatives market.
When approximately 97% of individual index-options turnover occurs within seven days of expiry, there is clearly a substantial concentration of individual activity at the shortest end of the derivatives market.
Making longer-duration contracts more capital-efficient could potentially encourage greater participation beyond this narrow expiry window.
But the success of any such policy should ultimately be assessed by whether it improves hedging activity, market depth, liquidity and the quality of derivatives participation — not simply whether trading volumes increase.
For now, traders should distinguish carefully between a regulatory discussion and an implemented rule.
Assisted Trading with Riddhi Siddhi Share Brokers
Trading Equity or F&O but finding it difficult to manage market movements, trade execution, entries and exits?
Explore Assisted Trading Services with Riddhi Siddhi Share Brokers for Trade Execution Support in Equity & Derivatives.
With Assisted Trading, trades remain in your own trading account, and you retain access through web and mobile trading platforms.
Connect with us for Assisted Trading Services:
Explore Riddhi Siddhi Share Brokers Services
WhatsApp: +91 99875 53455
Message +91 99875 53455 to request access to our exclusive WhatsApp community for daily prices, opportunities and market updates.
Visit Riddhi Siddhi Share Brokers.
Frequently Asked Questions
Has SEBI reduced F&O margins in September 2026?
No. SEBI is examining whether margin requirements for longer-term derivative contracts can be rationalised or potentially reduced. No new margin percentage or implementation date has been announced.
Will margins for long-term derivatives become lower?
That is not yet known. SEBI has indicated that margin requirements for longer-tenure derivative products are being examined. The eventual framework, eligible contracts and margin requirements have not been announced.
Does lower F&O margin mean lower risk?
No. A lower margin requirement means less capital may be required for an eligible position. It does not reduce the underlying market risk and can increase effective leverage.
Why is SEBI looking at longer-term derivatives?
SEBI has been seeking to deepen India’s derivatives markets while addressing concerns surrounding excessive short-term speculation. Its FY26 research also showed an extraordinary concentration of individual index-options turnover close to expiry.
What percentage of individual index-options turnover occurs close to expiry?
SEBI’s FY26 findings showed approximately 59% on expiry day and approximately 97% within seven days of expiry.
Are long-dated options safer than near-expiry options?
Not inherently. Their risk characteristics are different. Longer-dated options have more time remaining until expiry, while near-expiry options can experience very rapid premium changes. Both involve significant risks.
Should traders change their F&O strategy because of SEBI’s announcement?
There has been no margin-rule change yet. Traders should not assume that a regulatory review will necessarily result in a particular change or alter their strategy solely on that basis.
Conclusion
SEBI’s examination of margins for longer-term derivatives could become an important development for India’s F&O market.
But the most important fact today is simple:
Nothing has changed yet.
No new margin percentage, eligible tenure or implementation date has been announced.
The bigger question is what happens next.
When approximately 97% of individual index-options turnover occurs within seven days of expiry, developing a deeper market for longer-duration derivatives could potentially alter the structure of India’s F&O ecosystem.
Whether lower margins become part of that transition — and whether they actually change participant behaviour — will depend on the final regulatory framework.
Riddhi Siddhi Share Brokers will continue tracking these developments and explaining what they mean for traders and investors without confusing regulatory discussions with implemented rules.
Disclaimer
Riddhi Siddhi Share Brokers is an NSE & BSE Authorised Person of a leading broker. This article is for educational and informational purposes only and does not constitute investment, trading or financial advice. Futures and options involve substantial risk and may not be suitable for every investor or trader. Leverage can magnify both profits and losses. Past performance does not guarantee future results. Regulatory provisions and exchange requirements may change. Readers should verify the latest applicable SEBI and exchange circulars and consult a SEBI-registered investment adviser or other qualified professional where appropriate before making financial decisions.