The Reserve Bank of India has made an important change to the rules governing large institutional shareholdings in Indian banks.
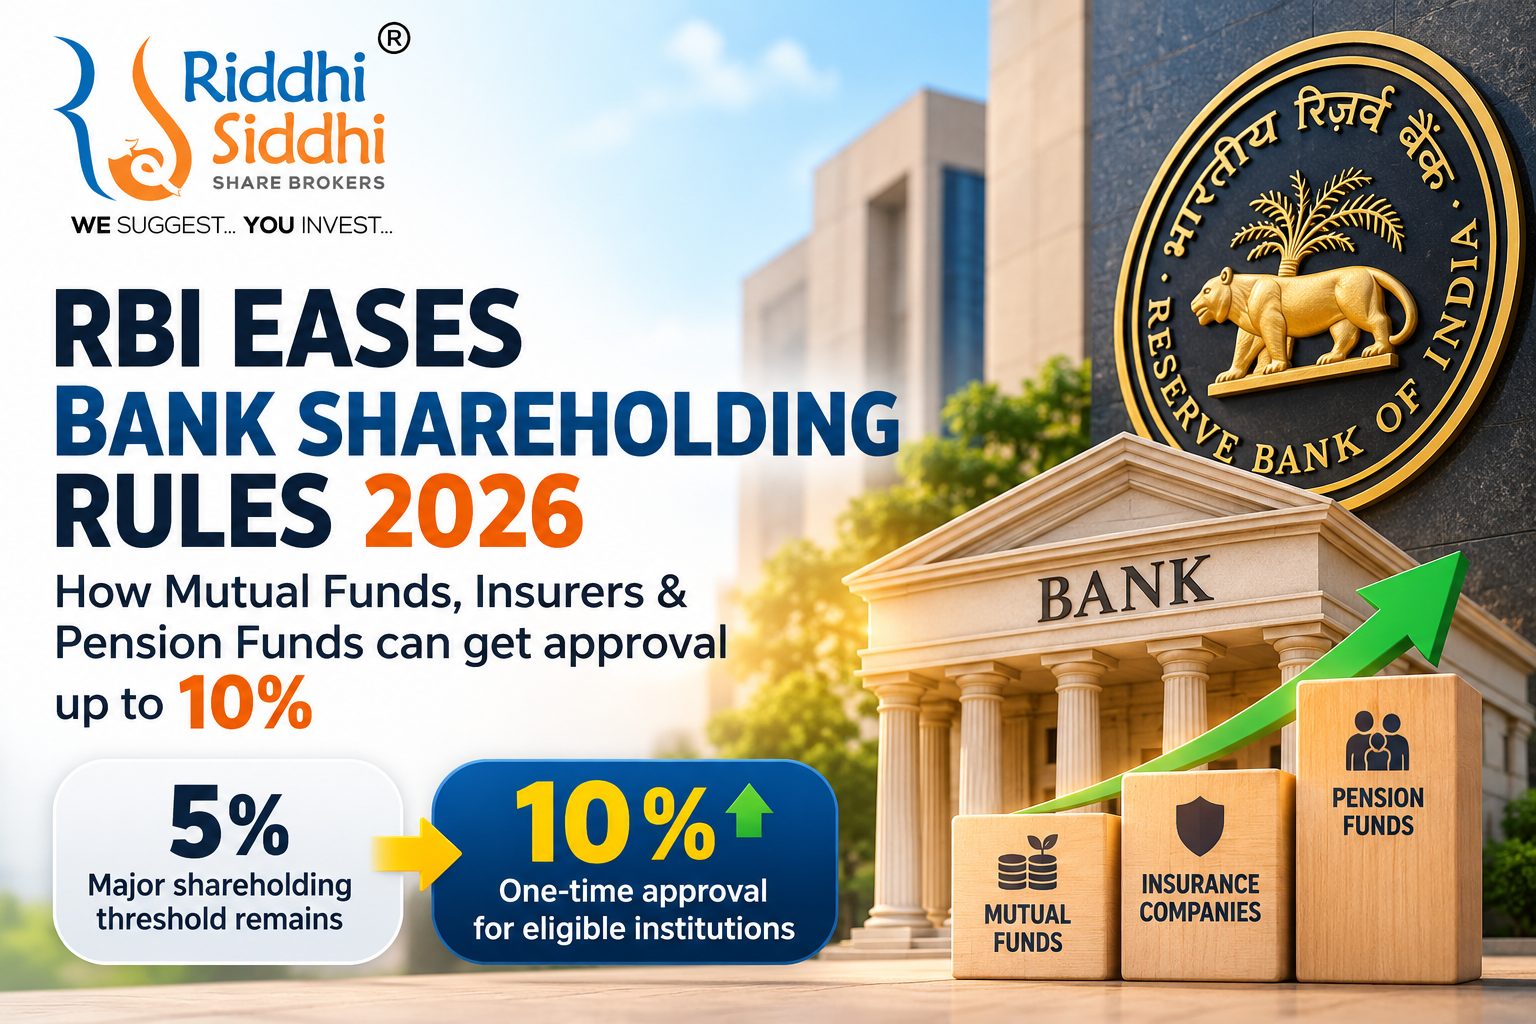
From October 1, 2026, eligible Mutual Funds, insurance companies and pension funds can seek a one-time RBI approval for subsequent acquisitions of major shareholding of up to 10% of a bank’s paid-up share capital or voting rights.
At first glance, this may sound like RBI has simply increased the bank ownership threshold from 5% to 10%.
That interpretation would be misleading.
The 5% threshold remains important. What RBI has changed is the approval process for certain regulated institutional investors that may move above, below and subsequently above the major-shareholding threshold.
So what exactly has changed? Can a Mutual Fund now own 10% of a bank? And does this mean institutional investors could start buying more bank stocks?
Riddhi Siddhi Share Brokers explains the new framework.
RBI Bank Shareholding Rule: 30-Second Answer
| Question | Answer |
|---|---|
| What is considered a major shareholding in a bank? | 5% or more of paid-up share capital or voting rights |
| Who can use the new one-time approval route? | Eligible Mutual Funds, insurance companies and pension funds |
| What can the one-time approval cover? | Subsequent acquisitions of major shareholding up to 10% |
| Is the initial acquisition automatically approved? | No |
| Has the 5% threshold simply been replaced by 10%? | No |
| Is RBI approval automatic? | No |
| Does the rule force institutions to buy bank stocks? | No |
| Does this directly change anything for retail investors? | No |
The most important point is therefore:
RBI has not simply doubled a 5% investment limit to 10%. The amendment primarily simplifies the approval process for subsequent acquisitions by qualifying institutional investors.
What Are RBI’s New Bank Shareholding Rules?
RBI issued the Reserve Bank of India (Commercial Banks – Acquisition and Holding of Shares or Voting Rights) Amendment Directions, 2026 on October 1, 2026.
The amendments came into force immediately.
Under the framework, a qualifying institutional investor can seek a one-time RBI approval covering subsequent acquisitions of major shareholding in the same bank up to 10% of its paid-up share capital or voting rights, calculated on an aggregate basis.
The eligible categories include:
- Mutual Funds registered with SEBI
- Pension funds registered with PFRDA
- Insurance companies registered with IRDAI
The approval remains subject to RBI’s conditions and continuing regulatory requirements.
Importantly, prior RBI approval continues to be mandatory for the initial acquisition of a major shareholding.
That distinction is crucial.
What Does the 5% Major Shareholding Threshold Mean?
Under RBI’s bank ownership framework, acquisition of 5% or more of a banking company’s paid-up share capital or voting rights constitutes a major shareholding.
The 2026 amendment does not make that concept disappear.
Under the earlier framework, once an investor had received approval for a major shareholding, its holding could later fall below 5%. If that investor subsequently wanted to acquire a major shareholding again, fresh prior approval could become necessary.
For large institutional investors whose holdings can change because of portfolio decisions, subscriptions, redemptions and market movements, repeated crossings of the threshold could therefore create additional regulatory steps.
RBI has now introduced a one-time approval mechanism for qualifying institutional investors for these subsequent acquisitions.
Old Framework vs New RBI Framework
| Particular | Earlier framework | New framework |
|---|---|---|
| Major-shareholding threshold | 5% or more | 5% or more |
| Prior approval for initial major shareholding | Required | Still required |
| Holding subsequently falls below 5% | Relevant for future approval requirement | Still subject to monitoring/reporting |
| Subsequent major acquisitions | Fresh approval could be required | Qualifying institutions can seek one-time approval |
| Maximum covered by one-time route | Not applicable | Up to 10% |
| RBI oversight | Yes | Yes |
| Automatic permission to own 10% | No | No |
In other words:
5% remains the major-shareholding threshold. The new 10% provision relates to the ceiling up to which RBI’s one-time approval can cover subsequent acquisitions by qualifying investors.
Can a Mutual Fund Now Own 10% of a Bank?
Potentially, subject to the applicable RBI framework and other regulatory conditions.
But saying simply that “Mutual Funds can now buy 10% of any bank” leaves out several important qualifications.
The institution must qualify under the framework, the relevant approval must be obtained, aggregate holdings matter, and RBI retains discretion over granting and continuing the approval.
The one-time approval may also be revoked for non-compliance with its terms and conditions or where the qualifying person, or a person associated with it, is subsequently found not to satisfy applicable “fit and proper” requirements.
Therefore, 10% should be understood as the ceiling covered by the one-time approval mechanism—not as an automatic entitlement or investment target.
Why Has RBI Introduced One-Time Approval?
The practical purpose is to reduce repeated regulatory approvals while retaining oversight of significant ownership in banks.
Institutional portfolios are dynamic.
A Mutual Fund’s aggregate exposure to a bank, for example, can change as different schemes buy or sell shares, investors subscribe or redeem units, or portfolios are rebalanced.
RBI’s revised framework allows qualifying regulated institutions to obtain one-time approval for subsequent acquisitions within the permitted ceiling instead of repeatedly going through the full approval process when their aggregate shareholding moves across the major-shareholding threshold.
At the same time, RBI continues to monitor these holdings.
An institution holding a one-time approval must report a decrease below or increase above the 5% threshold to RBI and the concerned bank within three working days of the event.
This is therefore better understood as regulatory simplification with continuing supervision, rather than deregulation of bank ownership.
Why Does This Matter for Mutual Funds?
Mutual Funds collectively manage large pools of investor capital and can become significant shareholders in listed companies.
But it is important to distinguish between the Mutual Fund structure and an individual investor’s investment decision.
The new RBI framework deals with institutional ownership of banks. It does not change how a retail investor selects a Mutual Fund.
Investors evaluating Mutual Funds should continue to consider factors such as investment objective, asset allocation, risk, time horizon, portfolio composition, expenses and historical consistency.
For readers comparing how different categories have actually performed over multiple periods, Riddhi Siddhi Share Brokers recently compiled a separate analysis of Mutual Fund Returns across 1, 3, 5 and 10 years.
Investors trying to understand the role of different fund categories can also read our guide on Small Cap, Mid Cap, Gold and other Mutual Fund categories for SIP investors.
Will the New RBI Rule Increase DII Buying in Bank Stocks?
Not necessarily.
This is perhaps the most important investment takeaway from the announcement.
The new framework removes a potential regulatory friction; it does not create an investment instruction.
A Mutual Fund, insurance company or pension fund will still make investment decisions based on its mandate and investment process.
Factors influencing institutional interest in a bank can include:
- Earnings growth
- Loan and deposit growth
- Net interest margins
- Asset quality
- Capital adequacy
- Return on assets and equity
- Management and governance
- Valuation
- Liquidity
- Portfolio concentration
- The institution’s own investment mandate
Therefore:
Easier regulatory approval does not automatically translate into institutional buying, and institutional buying does not guarantee that a bank’s share price will rise.
This distinction is particularly important in financial content, where a regulatory announcement should not be converted into a stock-market prediction.
Could This Still Be Positive for the Banking Market Structure?
The change could make it operationally easier for qualifying long-term institutional investors to manage meaningful positions in banking companies without repeatedly seeking approval after crossing the relevant threshold again.
That may reduce administrative friction.
However, the actual market impact will depend on whether institutions choose to use the framework and whether individual banks satisfy their investment criteria.
RBI also retains regulatory oversight.
Consequently, the amendment should not be interpreted as a signal from RBI about the attractiveness or future performance of any particular banking stock.
Readers interested in understanding another recent RBI action affecting India’s banking and financial markets can read Riddhi Siddhi Share Brokers’ explainer on RBI’s liquidity withdrawal and what excess banking-system liquidity means for rates, bonds and stocks.
What Does the New Rule Mean for Retail Bank Investors?
For an individual retail investor, there is no direct change to the ability to buy or sell listed bank shares because of this amendment.
The rule principally concerns large regulated institutional shareholdings.
Its relevance to retail investors is indirect.
Institutional ownership can be one factor worth understanding when analysing a listed company, but it should never be viewed in isolation.
A rising institutional stake does not automatically mean a stock is undervalued, and a falling institutional stake does not automatically make a stock unattractive.
Fundamentals and valuation still matter.
Does This Change the Rules for All Institutional Investors?
No.
The one-time approval mechanism specifically identifies qualifying regulated institutions such as eligible Mutual Funds, insurance companies and pension funds and operates subject to RBI’s stipulated requirements.
Investors should therefore avoid generalising the change to every domestic or foreign institutional shareholder.
Why the Difference Between 5% and 10% Matters
Headlines around regulatory changes frequently compress complicated rules into a single number.
Here, the numbers 5% and 10% describe different aspects of the framework.
5% remains relevant to what constitutes a major shareholding.
Up to 10% is the ceiling covered by the new one-time approval mechanism for subsequent acquisitions by qualifying institutional investors.
Understanding this distinction prevents a misleading conclusion that RBI has simply “doubled the Mutual Fund investment limit in banks.”
It has not.
Frequently Asked Questions
Has RBI increased the bank major-shareholding threshold from 5% to 10%?
No. The 5% threshold remains relevant for determining major shareholding. The amendment introduces a one-time approval mechanism for qualifying institutional investors covering subsequent acquisitions of major shareholding up to 10%.
Do Mutual Funds need RBI approval before initially acquiring 5% or more of a bank?
Yes. Prior RBI approval continues to be required for the initial acquisition of a major shareholding, subject to the applicable framework.
Which investors qualify for the new one-time approval route?
The framework covers qualifying Mutual Funds registered with SEBI, pension funds registered with PFRDA and insurance companies registered with IRDAI, subject to RBI’s conditions and eligibility requirements.
Is the 10% approval automatic?
No. RBI may grant the approval at its discretion, subject to applicable requirements and conditions.
Can RBI revoke the one-time approval?
Yes. RBI can revoke approval in circumstances including non-compliance with its conditions or relevant “fit and proper” concerns.
Does an institution have to report when its stake crosses 5%?
Qualifying institutions holding the one-time approval are required to report relevant movements below or above the 5% threshold to RBI and the concerned bank within three working days.
Will this make bank stocks rise?
The regulatory amendment by itself cannot establish the future direction of bank share prices. Valuation, earnings, asset quality, margins, economic conditions, institutional investment decisions and broader market conditions remain important.
Does this change anything for my Mutual Fund SIP?
Not directly. The amendment concerns institutional shareholding in banks, not the mechanics of an individual investor’s SIP. Investors reviewing their own Mutual Funds should continue to focus on goals, asset allocation, risk and investment horizon.
Bottom Line: Easier Approval Does Not Mean Automatic Buying
RBI’s October 1, 2026 amendment is significant, but the distinction matters.
The change is not simply “5% becomes 10%.”
The 5% major-shareholding threshold remains relevant.
What has changed is that eligible Mutual Funds, insurers and pension funds can seek one-time RBI approval for subsequent acquisitions of major shareholding up to 10%, subject to regulatory conditions and continuing oversight.
For institutional investors, that can reduce repeated approval requirements.
For retail investors, however, the announcement should not be treated as a signal to buy banking stocks.
At Riddhi Siddhi Share Brokers, we believe regulatory developments are most useful when investors understand what has actually changed—and equally importantly, what has not.
To explore Equity, Derivatives, Mutual Funds and other investment services, visit Riddhi Siddhi Share Brokers or explore our services.
For investors and traders who require execution support, learn more about our Assisted Trading Services.
Message +91 99875 53455 to request access to our exclusive WhatsApp community for daily prices, opportunities and market updates.
You can also connect with us for Assisted Trading Services and Trade Execution Support.
Disclaimer
Riddhi Siddhi Share Brokers is an NSE & BSE registered Authorised Person of a leading broker.
This article is published solely for educational and informational purposes and should not be construed as investment advice, research advice, a recommendation, solicitation or an offer to buy or sell any security or financial product. References to banks, Mutual Funds, institutional investors or market developments are for explanatory purposes only.
Investments in securities and Mutual Funds are subject to market risks. Past performance does not guarantee future returns. Regulatory provisions may also be amended or clarified from time to time. Readers should verify the latest applicable regulations and consult their financial/investment adviser before making investment decisions.