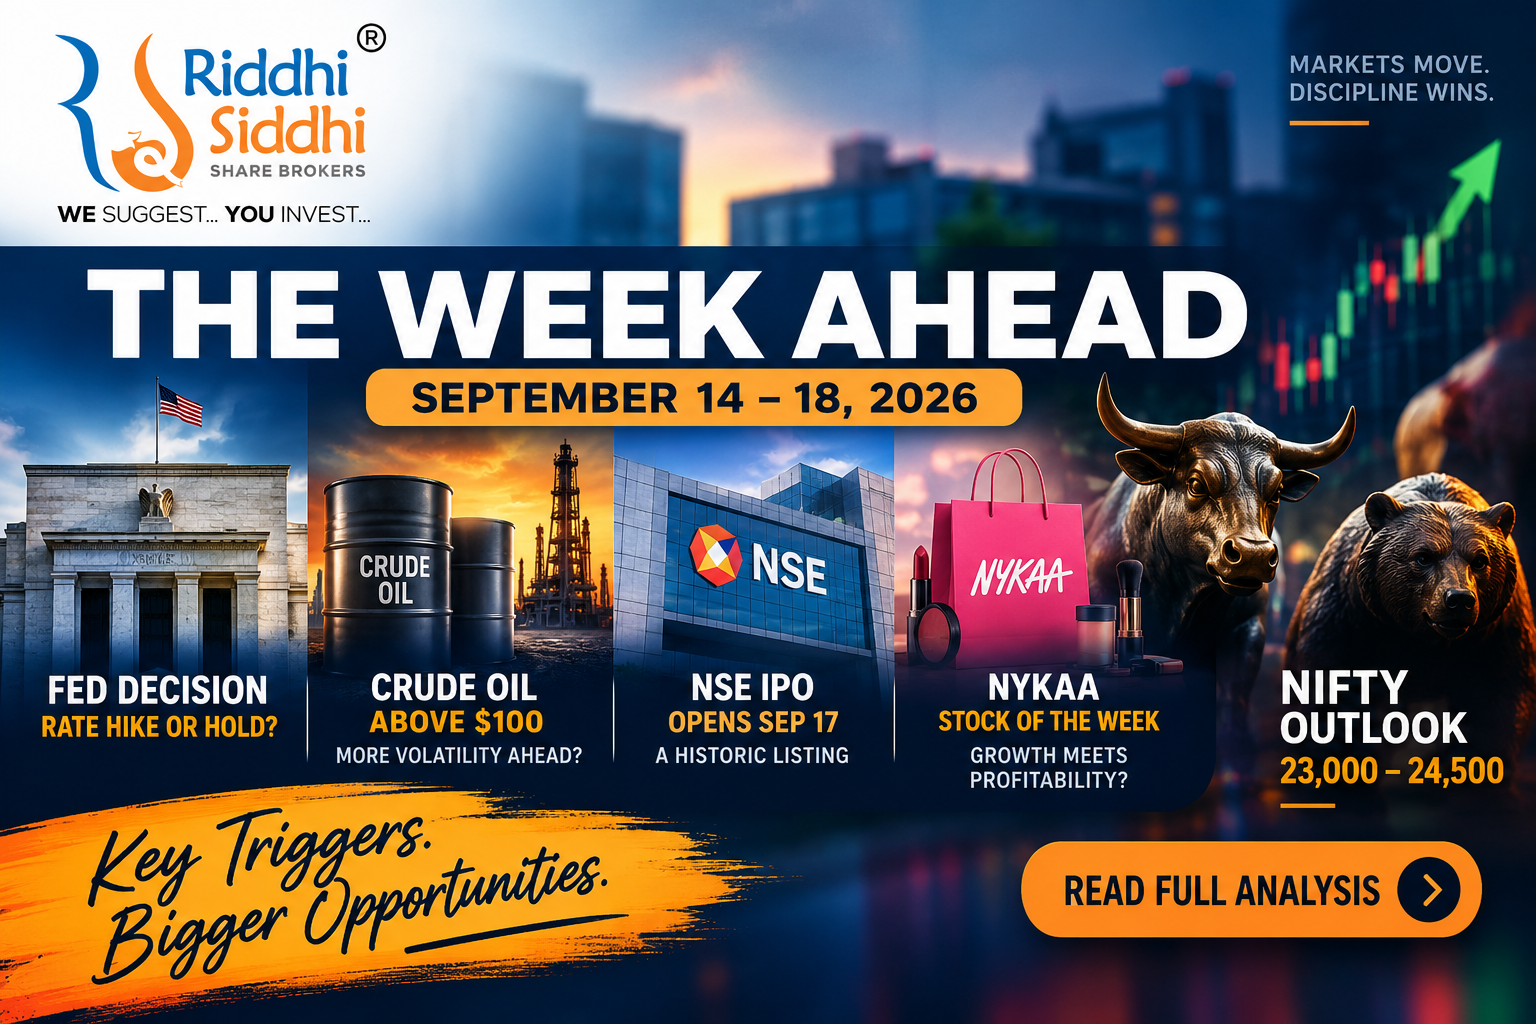
Riddhi Siddhi Share Brokers – The Week Ahead | Sunday, September 13, 2026
All Eyes on the FOMC Outcome!
Dalal Street enters one of the most important trading weeks of September with several major triggers converging at the same time:
The U.S. Federal Reserve’s September policy decision, India’s inflation data, crude oil above $100 amid continuing Middle East tensions, and the much-awaited NSE IPO.
The Nifty 50 closed Friday, September 11 at 23,398.10, leaving the index below several important technical resistance levels.
At Riddhi Siddhi Share Brokers, our near-term market stance remains cautious.
The technical structure continues to favour capital protection, disciplined position sizing and selective trading rather than aggressive bottom-fishing while Nifty remains below the important 24,000 resistance zone.
Riddhi Siddhi’s Market View | FOMC, Crude Oil & Geopolitics Take Centre Stage
The central question facing global markets this week is:
Can the Federal Reserve Avoid Another Rate Hike When Inflation Pressures Remain Elevated?
The Federal Reserve’s two-day policy meeting is scheduled for September 15–16, 2026, with the policy decision on Wednesday, September 16.
Markets will closely analyse not only the rate decision but also the updated economic projections, dot plot and commentary on inflation.
The Federal Funds target range currently stands at 3.50%–3.75%, but recent U.S. inflation numbers have strengthened expectations that the Fed could consider another 25-basis-point increase.
Whether the Fed actually hikes or delivers a hawkish hold, Wednesday could determine the direction of global equities, bonds, currencies and emerging-market capital flows.
Key Events This Week
Monday, September 14 | India CPI & WPI Inflation
India’s August inflation data will be the first major domestic macro trigger of the week.
Economists expect headline CPI inflation to accelerate from July levels, with food, fuel and elevated energy prices remaining important variables.
India’s WPI inflation data will also be released.
Why Does This Matter for Dalal Street?
A stronger-than-expected inflation print could:
- Reduce expectations of near-term RBI monetary easing.
- Put pressure on interest-rate-sensitive sectors.
- Increase concerns about corporate input costs.
- Add further pressure to the rupee if crude oil remains elevated.
A materially softer inflation number, however, could provide some relief to domestic equities.
Wednesday, September 16 | U.S. Federal Reserve Decision
The Federal Reserve’s September policy decision is likely to be the single biggest global market event of the week.
Markets will watch four things particularly closely:
1. Interest-Rate Decision
Will the Fed maintain the current 3.50%–3.75% range or increase rates by another 25 basis points?
2. Dot Plot
How many Federal Reserve policymakers expect further tightening?
3. Inflation Projections
Any upward revision to inflation expectations could strengthen the “higher for longer” interest-rate narrative.
4. Fed Commentary
Even if rates remain unchanged, hawkish commentary could potentially have almost the same market impact as an actual rate increase.
Riddhi Siddhi’s View | How the Fed Could Affect India
FII Liquidity
Higher U.S. interest rates and Treasury yields generally make dollar-denominated assets relatively more attractive.
A hawkish Fed could therefore put further pressure on foreign institutional flows into emerging markets such as India.
Conversely, a less-hawkish-than-feared outcome could trigger a relief rally across risk assets.
Indian Rupee & Imported Inflation
A stronger U.S. dollar combined with crude oil above $100 creates a difficult combination for India.
The transmission mechanism is important:
Crude Oil ↑ → Import Bill ↑ → Dollar Demand ↑ → Rupee Pressure ↑ → Imported Inflation ↑ → Corporate Margins ↓ → RBI Flexibility ↓
We recently examined this relationship in detail in Crude Oil Above $100, Rupee Above ₹95: What It Means for Nifty, Inflation & Indian Stocks.
For an oil-import-dependent economy such as India, crude oil therefore remains one of the most important external risks to watch.
Thursday, September 17 | NSE IPO Opens
One of India’s most anticipated capital-market events finally arrives this week.
The National Stock Exchange of India IPO is scheduled to open on September 17, 2026 and close on September 21, 2026.
NSE IPO – Key Details
Price Band: ₹1,700–₹1,785 per share
Lot Size: 8 shares
Minimum Retail Application at Upper Band: ₹14,280
Issue Structure: Offer for Sale (OFS)
Opening Date: September 17, 2026
Closing Date: September 21, 2026
Listing Exchange: BSE
The IPO is particularly interesting because NSE shares had traded at substantially higher prices in the unlisted market before the official IPO price band was announced.
For the public-market perspective, read NSE IPO 2026: Price, Dates, SEBI Approval & What Investors Should Know.
For investors who bought NSE shares in the unlisted market, VaultStreet Advisors has separately analysed the valuation gap in Bought NSE Unlisted Shares Above ₹2,000? What the ₹1,785 IPO Price Could Mean for Investors.
This is an important real-world reminder:
Unlisted-Market Price ≠ IPO Price ≠ Guaranteed Listing Price
The wider IPO boom also does not automatically translate into higher prices or liquidity across the unlisted market. Read IPO Boom, Unlisted Slowdown: What India’s ₹70,000 Crore September Rush Means for Pre-IPO Investors for the broader perspective.
Riddhi Siddhi’s Call of the Week
The Fed + Crude Oil Combination Could Decide the Next Major Nifty Move
A Fed rate hike—or even a strongly hawkish hold—could push U.S. Treasury yields higher, strengthen the dollar and maintain pressure on emerging-market equities.
A less-hawkish-than-feared outcome, cooling crude oil prices or geopolitical de-escalation could instead produce a sharp relief rally.
This is therefore a week where traders should be prepared for event-driven volatility in both directions.
What the Bulls Need
- A dovish or less-hawkish-than-feared Federal Reserve outcome.
- Cooling crude oil prices.
- De-escalation in geopolitical tensions.
- Stabilisation of the Indian rupee.
- Revival in institutional buying.
- Nifty reclaiming and sustaining above the 24,000 zone.
Riddhi Siddhi’s Gyan Mantra
Protect capital first. Opportunities will always return.
With geopolitical uncertainty elevated and the Federal Reserve decision approaching, traders should avoid excessive leverage and resist bottom-fishing solely because prices have declined sharply.
Volatility can create opportunity—but only if capital survives the volatility.
Riddhi Siddhi’s Nifty Outlook
Nifty 50 | CMP: 23,398
Support: 23,000 / 22,722
Resistance: 23,651 / 24,000
Near-Term Range: 23,103–23,522
200 DMA: ~24,544
Bias: Negative below 24,000
The options structure highlights the importance of the 24,000 Call strike as a major resistance zone, while the 23,000 Put strike remains an important support area.
The broader derivatives structure suggests that Nifty could remain within an extended 22,500–24,500 zone, although event-driven volatility around the Federal Reserve decision can temporarily push the index beyond normal technical ranges.
The key level remains 24,000.
Until Nifty decisively reclaims this zone, rallies could continue to face selling pressure.
For context on how the present technical setup developed, read our previous Week Ahead: Nifty Outlook, US CPI, Crude Oil & JSW Steel | September 7–11, 2026.
Riddhi Siddhi’s Bank Nifty Outlook
Bank Nifty | CMP: ~56,607
Support: 55,750 / 54,000
Resistance: 57,500 / 59,000
Near-Term Range: 55,800–57,488
200 DMA: ~57,371
Bias: Cautious to Negative
Bank Nifty staged an impressive recovery from Friday’s intraday lows.
However, the index needs to reclaim the 57,400–57,500 zone before the technical structure begins looking materially stronger.
A break below 55,750 could once again increase downside pressure.
Riddhi Siddhi’s Preferred Trading View for the Week
Nifty | 23,398
Our technical framework remains bearish while Nifty stays below the 23,650–24,000 resistance zone.
Downside Reference Levels: 23,000 / 22,722
Aggressive Downside Zone: 22,260–22,300
Technical Invalidation Zone: Above approximately 23,675
These are technical reference levels and market scenarios—not guaranteed outcomes or personalised trading recommendations.
Position sizing and stop-loss discipline become especially important during a week containing a major central-bank decision and geopolitical uncertainty.
Riddhi Siddhi’s Sector Outlook
Relatively Stronger / Defensive
Healthcare
Pharmaceuticals
These sectors could remain relatively resilient if global risk aversion stays elevated.
Sectors Facing Greater Near-Term Pressure
FMCG
Automobiles
Real Estate
Energy-sensitive Businesses
Information Technology
Sector views should not be interpreted as blanket recommendations because individual companies within the same sector can perform very differently.
Riddhi Siddhi’s Stocks in Focus
Positive Technical Watchlist
DR REDDY’S | BEL | BHEL | AU SMALL FINANCE BANK | FEDERAL BANK | CG POWER
Cautious / Weak Technical Watchlist
PI INDUSTRIES | APL APOLLO | SBI CARDS | KEI INDUSTRIES | GRASIM | LTIMINDTREE | MUTHOOT FINANCE | GODREJ PROPERTIES | LODHA | OBEROI REALTY | COCHIN SHIPYARD | MARUTI SUZUKI | GODFREY PHILLIPS | PRESTIGE ESTATES | CUMMINS INDIA | POLYCAB | SRF
These stocks are highlighted based on their current technical structures and should not be interpreted as personalised buy or sell recommendations.
Riddhi Siddhi’s Stock of the Week | NYKAA
FSN E-Commerce Ventures Ltd. – A Growth Story Becoming an Earnings Story
Reference CMP: ~₹344–₹345
52-Week High: ~₹350
Market Capitalisation: ~₹98,000+ crore
Risk Profile: Moderate–High
Nykaa remains one of the most interesting consumer-internet businesses in the Indian listed market.
The stock is trading close to its 52-week high, which makes one fundamental question especially important:
Can Nykaa’s Earnings Grow Fast Enough to Justify Its Premium Valuation?
At Riddhi Siddhi Share Brokers, we believe the answer increasingly depends on margin expansion rather than revenue growth alone.
Profitability Is Finally Catching Up With Growth
Nykaa delivered a strong Q1 FY27 performance.
| Particulars | Q1 FY27 | YoY Growth |
|---|---|---|
| Revenue | ₹2,782 crore | +29% |
| EBITDA | ₹236 crore | +68% |
| EBITDA Margin | 8.5% | ~+200 bps |
| PAT | ~₹80 crore | >3x |
| Beauty NSV | ~₹2,371 crore | ~+29% |
| Fashion NSV | ~₹451 crore | ~+54% |
The most encouraging number isn’t simply the 29% revenue growth.
It is the much faster growth in EBITDA.
Revenue +29% → EBITDA +68%
That is what operating leverage should begin to look like.
If revenue continues growing above 20% while EBITDA grows substantially faster, Nykaa could gradually grow into part of its premium valuation.
Catalyst 1 | Fashion Is No Longer Just the Problem Child
Nykaa Fashion historically diluted consolidated profitability.
That picture is changing.
Fashion NSV grew approximately 54% YoY during Q1 FY27, while the division remained marginally EBITDA-positive.
If Fashion develops from a margin drag into a sustainably profitable growth business, Nykaa could benefit twice:
Higher Growth + Lower Consolidated Margin Drag
This could become one of the most important earnings catalysts to monitor through FY27.
Catalyst 2 | Beauty Remains Nykaa’s Moat
Beauty & Personal Care remains Nykaa’s crown jewel.
The platform benefits from:
- Premiumisation.
- Repeat purchases.
- Strong customer trust.
- Global-brand partnerships.
- Owned brands.
- Higher-value beauty categories.
- Omnichannel distribution.
- First-party customer data.
Beauty NSV increased approximately 29% YoY during Q1 FY27.
Nykaa’s combination of online distribution and physical stores creates an important competitive advantage because premium beauty frequently benefits from physical discovery, assisted selling and customer trust.
Catalyst 3 | House of Nykaa Could Create Significant Value
Nykaa is increasingly becoming more than a marketplace selling other companies’ products.
Its owned-brand ecosystem includes names such as:
Nykaa Cosmetics | Kay Beauty | Dot & Key
Successful owned brands can potentially deliver stronger economics than simply operating as a third-party marketplace.
Owned Brands → Higher Margins → Customer Loyalty → Pricing Power → Better Economics
If Nykaa can continue scaling these brands without materially increasing customer-acquisition costs, the House of Nykaa portfolio could become an increasingly valuable part of the overall business.
Catalyst 4 | Omnichannel Expansion
Nykaa has expanded its physical network to more than 320 stores across 100+ cities.
Offline retail is particularly relevant for beauty.
Customers often want to:
Discover → Test → Experience → Buy → Reorder Online
This gives Nykaa an increasingly integrated ecosystem:
Beauty + Fashion + Retail + Owned Brands + B2B
Nykaa should therefore increasingly be evaluated as an omnichannel consumer platform rather than simply an e-commerce website.
Catalyst 5 | AI Could Support Margin Expansion
Nykaa is also increasing its use of artificial intelligence across customer experience and business operations.
But investors should ignore the AI buzzword and focus on measurable outcomes.
Can AI improve:
Personalisation?
Conversion Rates?
Inventory Planning?
Marketing Efficiency?
Customer Support Costs?
Customer Acquisition Economics?
If the answer becomes yes, AI could contribute directly to Nykaa’s bigger investment thesis:
Margin Expansion.
Riddhi Siddhi’s Biggest Positive | Operating Leverage
This is where we see the strongest case for a potential fundamental rerating.
The earnings architecture is becoming increasingly interesting:
Revenue ↑
Scale ↑
Marketing Efficiency ↑
Fashion Losses ↓
EBITDA Margin ↑
PAT Grows Faster Than Revenue ↑
Nykaa’s Q1 FY27 EBITDA margin reached approximately 8.5%, compared with around 6.5% in the corresponding period.
If the margin trajectory continues, the earnings story could become considerably stronger.
Riddhi Siddhi’s Biggest Concern | Valuation
This cannot be ignored.
At approximately ₹344–₹345, Nykaa continues to command an exceptionally rich conventional earnings valuation.
That means the market is already discounting several years of:
High Revenue Growth + Margin Expansion + Fashion Improvement + Owned-Brand Growth
Consequently:
One or Two Disappointing Quarters Could Result in Substantial Valuation Compression
A good company is not automatically a good investment at every price.
Entry valuation still matters.
Interestingly, this is the same principle VaultStreet Advisors recently examined while analysing NSE’s ₹1,785 IPO Price Versus Unlisted Prices Above ₹2,000.
Whether analysing a listed company or an unlisted one, business quality and entry valuation must be considered separately.
Other Key Risks for NYKAA
Investors should monitor:
- Extreme valuation.
- Aggressive competition in beauty and e-commerce.
- Higher customer-acquisition expenditure.
- Slower discretionary consumption.
- Failure of Fashion margins to improve sustainably.
- Execution risk from acquisitions and new businesses.
- Slower Beauty growth.
- Margin pressure from quick-commerce competitors.
The stock has already rallied substantially and is trading close to recent highs, meaning part of the improving earnings story may already be reflected in the price.
What Could Take NYKAA Towards the ₹400 Zone?
For the bullish thesis to strengthen over the next 9–12 months, we would particularly monitor four numbers:
1. Consolidated Revenue Growth Sustaining Around 20–25%+
2. Beauty Maintaining Strong Growth
3. Fashion Remaining Profitable
4. Consolidated EBITDA Margin Progressing Towards or Above 9%
If these occur simultaneously, earnings upgrades could potentially provide support for a further rerating.
However, if revenue growth slips materially or margin expansion stalls, the premium valuation becomes considerably harder to defend.
Riddhi Siddhi’s NYKAA Framework
FSN E-Commerce Ventures Ltd. | NYKAA
Reference CMP: ~₹344–₹345
Immediate Technical Zones: ₹363 / ₹377
Higher Technical Zone: ₹400–₹421
Preferred Accumulation Zone on Meaningful Corrections: ~₹305–₹315
Risk Level: Moderate–High
Time Horizon: 9–12 Months
These are scenario-based technical reference levels rather than assured price targets.
Given Nykaa’s valuation and proximity to recent highs, investors should avoid chasing the stock solely because of momentum.
The risk-reward could become more favourable during meaningful corrections provided the earnings and margin thesis remains intact.
Riddhi Siddhi’s Bottom Line
The week of September 14–18 could be one of the most important market weeks of the month.
Three variables may determine the direction of Indian equities:
Federal Reserve Policy
Crude Oil
Geopolitics
India’s inflation numbers and the opening of the historic NSE IPO add another layer of potential volatility.
Our broader market stance remains cautious while Nifty stays below 24,000.
At the individual-stock level, Nykaa’s fundamental story is becoming increasingly interesting because earnings are beginning to grow materially faster than revenue.
But valuation remains the biggest risk.
Protect Capital. Avoid Excessive Leverage. Let Price Confirm the Next Trend.
Looking for Assisted Trading Support?
In volatile markets, identifying a trade is only one part of the process. Execution, position sizing, risk management and discipline can be equally important.
Riddhi Siddhi Share Brokers provides Assisted Trading Services across eligible market segments.
👉 Explore Riddhi Siddhi Share Brokers Assisted Trading Services
📞 Call / WhatsApp: +91 91379 69859
We Suggest… You Invest.
Join Our Market Community
Message +91 99875 53455 to request access to our exclusive WhatsApp community for daily prices, opportunities and market updates.
Disclaimer
Riddhi Siddhi Share Brokers is an NSE & BSE Authorised Person of a leading broker.
This article is intended solely for educational and informational purposes and should not be construed as investment advice, research advice, personalised financial advice, a solicitation, or a recommendation to buy, sell or hold any security.
The market outlook, sector views, stock watchlists, technical levels and price scenarios discussed above represent educational market observations based on prevailing market conditions and may change without notice.
Investments in securities markets are subject to market risks. Derivatives involve significant risk and can result in substantial losses and may not be suitable for all investors.
References to technical levels, potential price zones or market scenarios do not constitute any assurance or guarantee of future performance. Past performance is not indicative of future returns.
Investors should conduct their own due diligence and, where appropriate, consult a SEBI-registered Investment Adviser or other appropriately registered market intermediary before making investment decisions.
Registration granted by SEBI and certification from NISM do not guarantee the performance of an intermediary or provide any assurance of returns.
Riddhi Siddhi Share Brokers
We Suggest… You Invest.