Foreign investors are selling India?
September 2026 tells a much more interesting story.
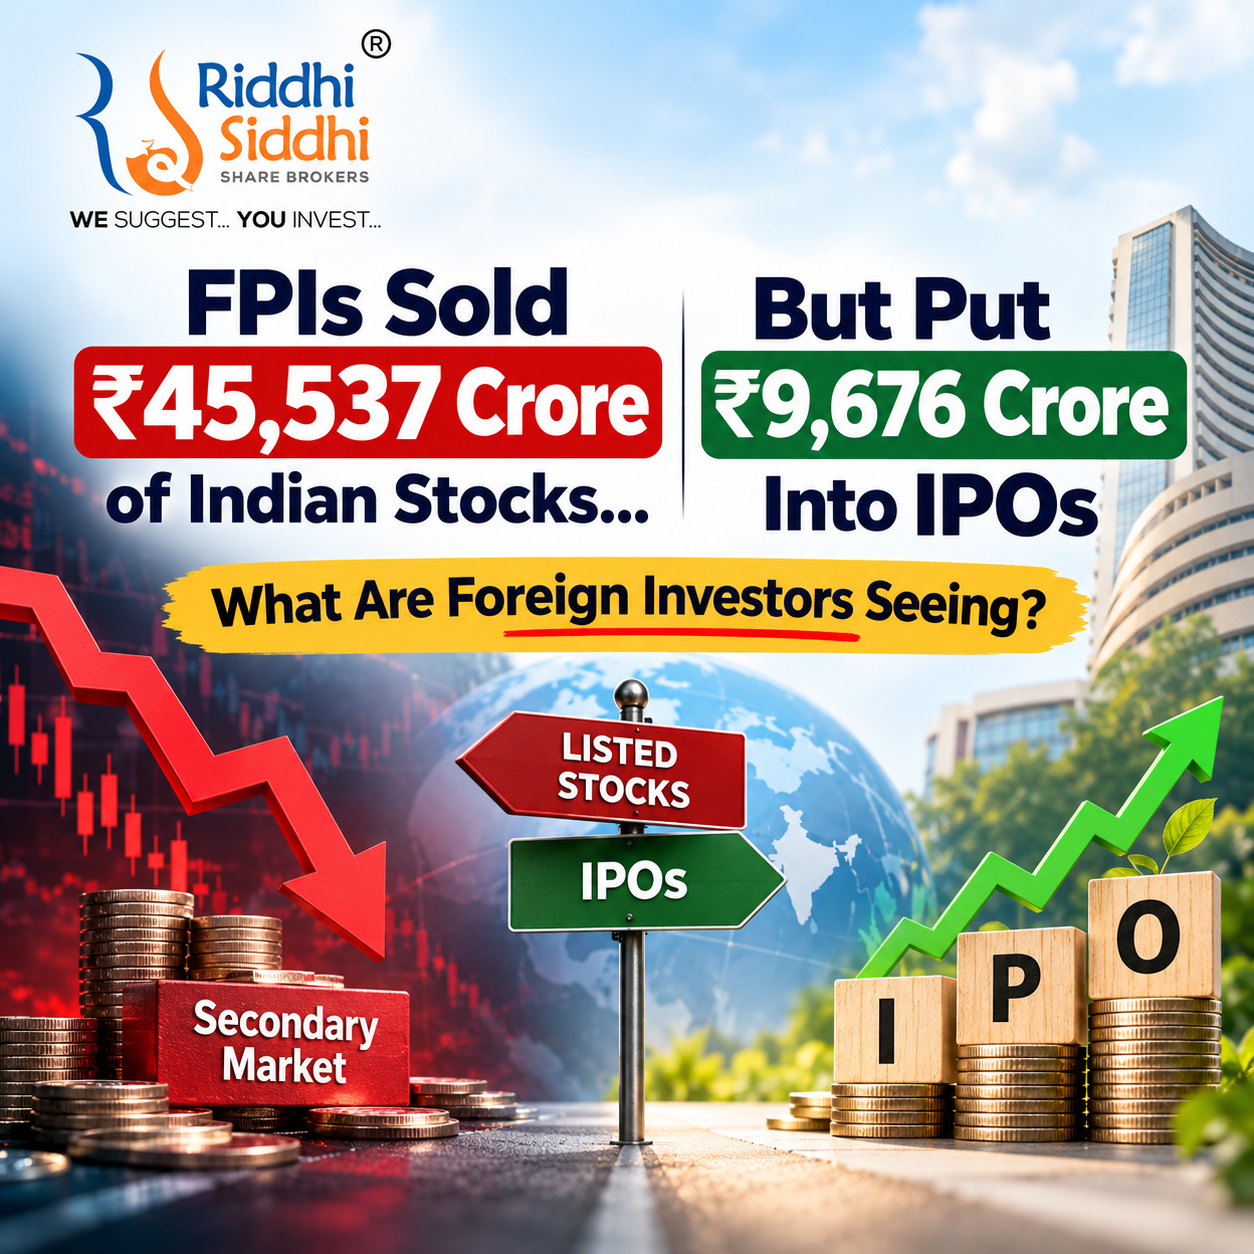
Foreign Portfolio Investors (FPIs) sold approximately ₹45,537 crore of Indian equities through the secondary market during September.
But during the same month, they invested approximately ₹9,676 crore in India’s primary market, including IPOs and other new issuances.
So the real question isn’t simply:
Why are FPIs selling Indian stocks?
The more interesting question is:
Why Are FPIs Selling Listed Indian Stocks While Still Buying IPOs?
The answer lies in understanding that India is not one single investment decision for a foreign investor.
FPIs can reduce exposure to already-listed Indian stocks because of valuations, global interest rates, currency movements or portfolio allocation—and at the same time selectively invest in attractive new issues.
In other words:
Selling listed India does not necessarily mean rejecting India.
It may instead mean foreign investors are becoming more selective about where and at what valuation they want exposure to India.
FPI Flows in September 2026: The Numbers
| September 2026 FPI Equity Flow | Approximate Amount |
|---|---|
| Primary-market investment | +₹9,676 crore |
| Secondary-market selling | −₹45,537 crore |
| Net equity flow after both | −₹35,861 crore |
| Secondary-market equivalent | −$4.8 billion |
| Primary-market equivalent | +$1 billion |
| What does it indicate? | Very different FPI appetite for new issues and existing listed stocks |
This distinction is important.
A headline saying “FPIs sold ₹45,537 crore” tells only one part of the story.
Foreign investors were simultaneously committing fresh capital to India’s primary market.
What Is the Difference Between Primary-Market and Secondary-Market FPI Flows?
The distinction is relatively simple.
Primary Market
The primary market is where securities are offered to investors as part of a new issuance or public offering.
Examples include:
- IPOs
- Follow-on Public Offers (FPOs)
- Qualified Institutional Placements (QIPs)
- Other new issuances
Depending on the structure of an issue, money raised may go to the company, existing shareholders selling shares, or a combination of both.
Secondary Market
The secondary market is where investors buy and sell shares that are already listed.
When an FPI buys or sells shares of a listed company through the stock exchange, that activity forms part of secondary-market flows.
September 2026: Primary vs Secondary Market
| Question | Primary Market | Secondary Market |
|---|---|---|
| What is being bought? | New issues / offered securities | Already-listed shares |
| Examples | IPO, FPO, QIP | NSE/BSE stock trades |
| September FPI direction | Net buying | Heavy selling |
| Approx. September flow | +₹9,676 crore | −₹45,537 crore |
| Does one automatically predict the other? | No | No |
That explains why apparently contradictory headlines can both be correct.
If FPIs Are Selling India, Why Are They Buying IPOs?
There is no single explanation applicable to every foreign investor or every IPO.
But several factors can explain the divergence.
1. Every IPO Is Evaluated Separately
Institutional investors do not necessarily view an IPO as simply another bet on the Nifty.
They can evaluate:
- the company’s business model
- industry opportunity
- financial performance
- management
- growth prospects
- issue structure
- valuation
- institutional allocation
- potential portfolio fit
An investor can therefore be cautious about the overall listed market while still finding a particular new issue attractive.
The same principle applies to retail investors.
With several public issues competing for attention, an IPO should be assessed on its business, financials, valuation, offer structure, use of proceeds and risks—not merely on market excitement or Grey Market Premium.
Our earlier guide on how to choose an IPO without following GMP blindly explains this framework in detail.
Importantly, primary-market buying does not mean every IPO is cheap or attractive.
Every issue needs to be evaluated independently.
2. Valuation Matters
One reason foreign investors can sell existing holdings is valuation.
A fundamentally strong company can still become less attractive to an investor if its valuation moves significantly above what that investor considers reasonable.
An IPO presents a different valuation decision.
That can create a situation where an institution reduces exposure to some listed holdings while allocating capital to selected new opportunities.
But even in an IPO, valuation cannot be reduced to one number.
As we explained in our analysis of IPO P/E ratios versus IPO returns, P/E is an important valuation metric but cannot by itself predict listing gains or subsequent share-price performance.
For FPIs too, valuation is one part of a broader investment decision.
3. FPIs Continuously Rebalance Portfolios
Foreign institutional portfolios are not static.
Money is constantly reallocated between:
- countries
- sectors
- currencies
- asset classes
- individual companies
- developed and emerging markets
An FPI may therefore sell Indian secondary-market holdings without taking a permanently bearish view on India.
It may simply be changing the size or composition of its India allocation.
Why Are Foreign Investors Selling Listed Indian Stocks?
The answer extends beyond India.
Foreign capital continuously compares the potential return from Indian equities with opportunities available globally.
Several variables currently matter.
US Treasury Yields
Higher US bond yields can increase the attractiveness of dollar-denominated fixed-income assets and influence global equity allocations.
We have explained this relationship in detail in our analysis of how US Treasury yields affect Indian stocks, FII/FPI flows, the rupee and market valuations.
When relatively lower-risk US assets offer higher yields, the hurdle rate for investing in emerging-market equities can rise.
Crude Oil
India is a major importer of crude oil.
Higher crude prices can affect:
- inflation expectations
- the current account
- the rupee
- corporate margins
- interest-rate expectations
Sustained strength in crude can therefore influence foreign investors’ assessment of Indian equities.
The Rupee
Currency movements matter significantly to overseas investors.
An FPI’s ultimate return is not determined only by the movement in an Indian stock.
The rupee-dollar exchange rate can also affect the investor’s return when capital is converted back into dollars.
Consequently, expectations about currency depreciation or appreciation can influence foreign portfolio allocations.
Indian Equity Valuations
Foreign investors compare Indian valuations not only with India’s own historical valuations but also with competing global markets.
Strong long-term economic prospects do not automatically mean investors will accept any valuation.
A positive long-term view on India and short-term selling of Indian equities can exist simultaneously.
Does ₹45,537 Crore of FPI Selling Mean Nifty Must Keep Falling?
No.
FPI flows are important, but they are only one component of market liquidity and price discovery.
Domestic Institutional Investors (DIIs), mutual funds, retail investors, proprietary investors and other market participants also influence prices.
Heavy FPI selling can create pressure, but it does not mechanically determine where Nifty must trade next.
For the immediate market setup—including important Nifty support and resistance zones, the RBI policy decision, FII flows, crude oil and Q2 earnings triggers—read our latest Nifty Week Ahead October 5–9, 2026.
Are FPIs Actually Bearish on India?
The September numbers suggest the answer is more nuanced than a simple yes or no.
Consider the two numbers again:
Secondary market: −₹45,537 crore
Primary market: +₹9,676 crore
The combined equity flow was therefore still negative.
But the simultaneous primary-market investment tells us something important: foreign investors were not treating every Indian equity opportunity in the same way.
Instead, the numbers point towards selectivity.
FPIs can simultaneously be:
cautious about certain listed-market valuations
and
interested in selected new Indian investment opportunities.
Those are not contradictory positions.
Can India’s IPO Boom Affect Existing Listed Stocks?
Potentially, yes.
A very large pipeline of new equity issuance can compete for investor capital.
Every large IPO, FPO or other issuance requires money to be allocated somewhere.
When primary-market fundraising becomes substantial, some investors may rebalance existing portfolios to participate in new issues.
This does not mean every rupee entering an IPO comes out of the secondary market.
But the size of the primary-market pipeline can become an important liquidity variable.
We previously discussed the broader impact of primary-market supply while examining the factors that could determine whether Nifty can reach 26,200 by December 2026.
Should Retail Investors Follow FII and FPI Buying and Selling?
FPI data can be useful.
But it should not be treated as a standalone trading signal.
A common oversimplification is:
FII buying = market must rise
or
FII selling = market must fall
Markets are more complicated.
Investors should consider FPI flows alongside:
- price action
- valuations
- corporate earnings
- domestic institutional flows
- interest rates
- crude oil
- currency movements
- global risk sentiment
- company-specific fundamentals
Most importantly, a daily FPI number does not tell you the complete reasoning behind thousands of institutional transactions.
What Can Retail Investors Learn From September’s FPI Numbers?
Perhaps the most important lesson is that capital is selective.
The September data demonstrate why investors should avoid treating phrases such as “foreign investors are leaving India” as complete investment analysis.
FPIs sold approximately ₹45,537 crore in the secondary equity market, yet simultaneously invested around ₹9,676 crore in the primary market.
The same broad category of investors was therefore selling one part of the Indian equity opportunity while buying another.
That distinction matters.
Bottom Line: Foreign Investors Aren’t Treating All of India the Same Way
September 2026 produced a fascinating divergence.
₹45,537 crore OUT of the secondary equity market.
₹9,676 crore IN through the primary market.
Net equity flow: approximately ₹35,861 crore OUT.
The numbers do not tell us that foreign investors are universally bullish or bearish on India.
They tell us something more useful:
FPIs are being selective about where they deploy capital.
Global yields, crude oil, currency movements, valuations and portfolio allocation can encourage foreign investors to reduce existing holdings.
At the same time, individual IPOs and new issuances can continue attracting institutional capital.
That is why looking only at the headline daily FII/FPI number can give investors an incomplete picture.
The better question isn’t simply whether foreign investors are buying or selling India.
It is: where are they putting their money—and why?
Connect With Riddhi Siddhi Share Brokers for Assisted Trading
Markets can become difficult to navigate when institutional flows, global cues, earnings and price action start pulling in different directions.
If you want structured trade execution support while retaining control over your own trading decisions, explore our Assisted Trading Services.
You Decide. We Support.
📲 Call / WhatsApp: +91 91379 69859
🌐 www.riddhisiddhisharebrokers.com
Riddhi Siddhi Share Brokers
We Suggest… You Invest.
Disclaimer
This article is for educational and informational purposes only and should not be construed as investment advice or a recommendation to buy, sell or hold any security.
Riddhi Siddhi Share Brokers is an NSE & BSE Authorised Person of a leading broker and does not provide investment advisory services. Investors should conduct their own research and/or consult a SEBI-registered investment adviser before making investment decisions.
Investments in securities markets are subject to market risks. Past performance does not guarantee future returns.